The Simple New Roadmap Women Business Owners at $15K+/Month Are Using to Get Business Credit Reporting in Their Company's Name in 90 Days, Without an LLC That Stops at the Filing
Why the LLC you already filed isn't the problem, and why the owner named on it is.
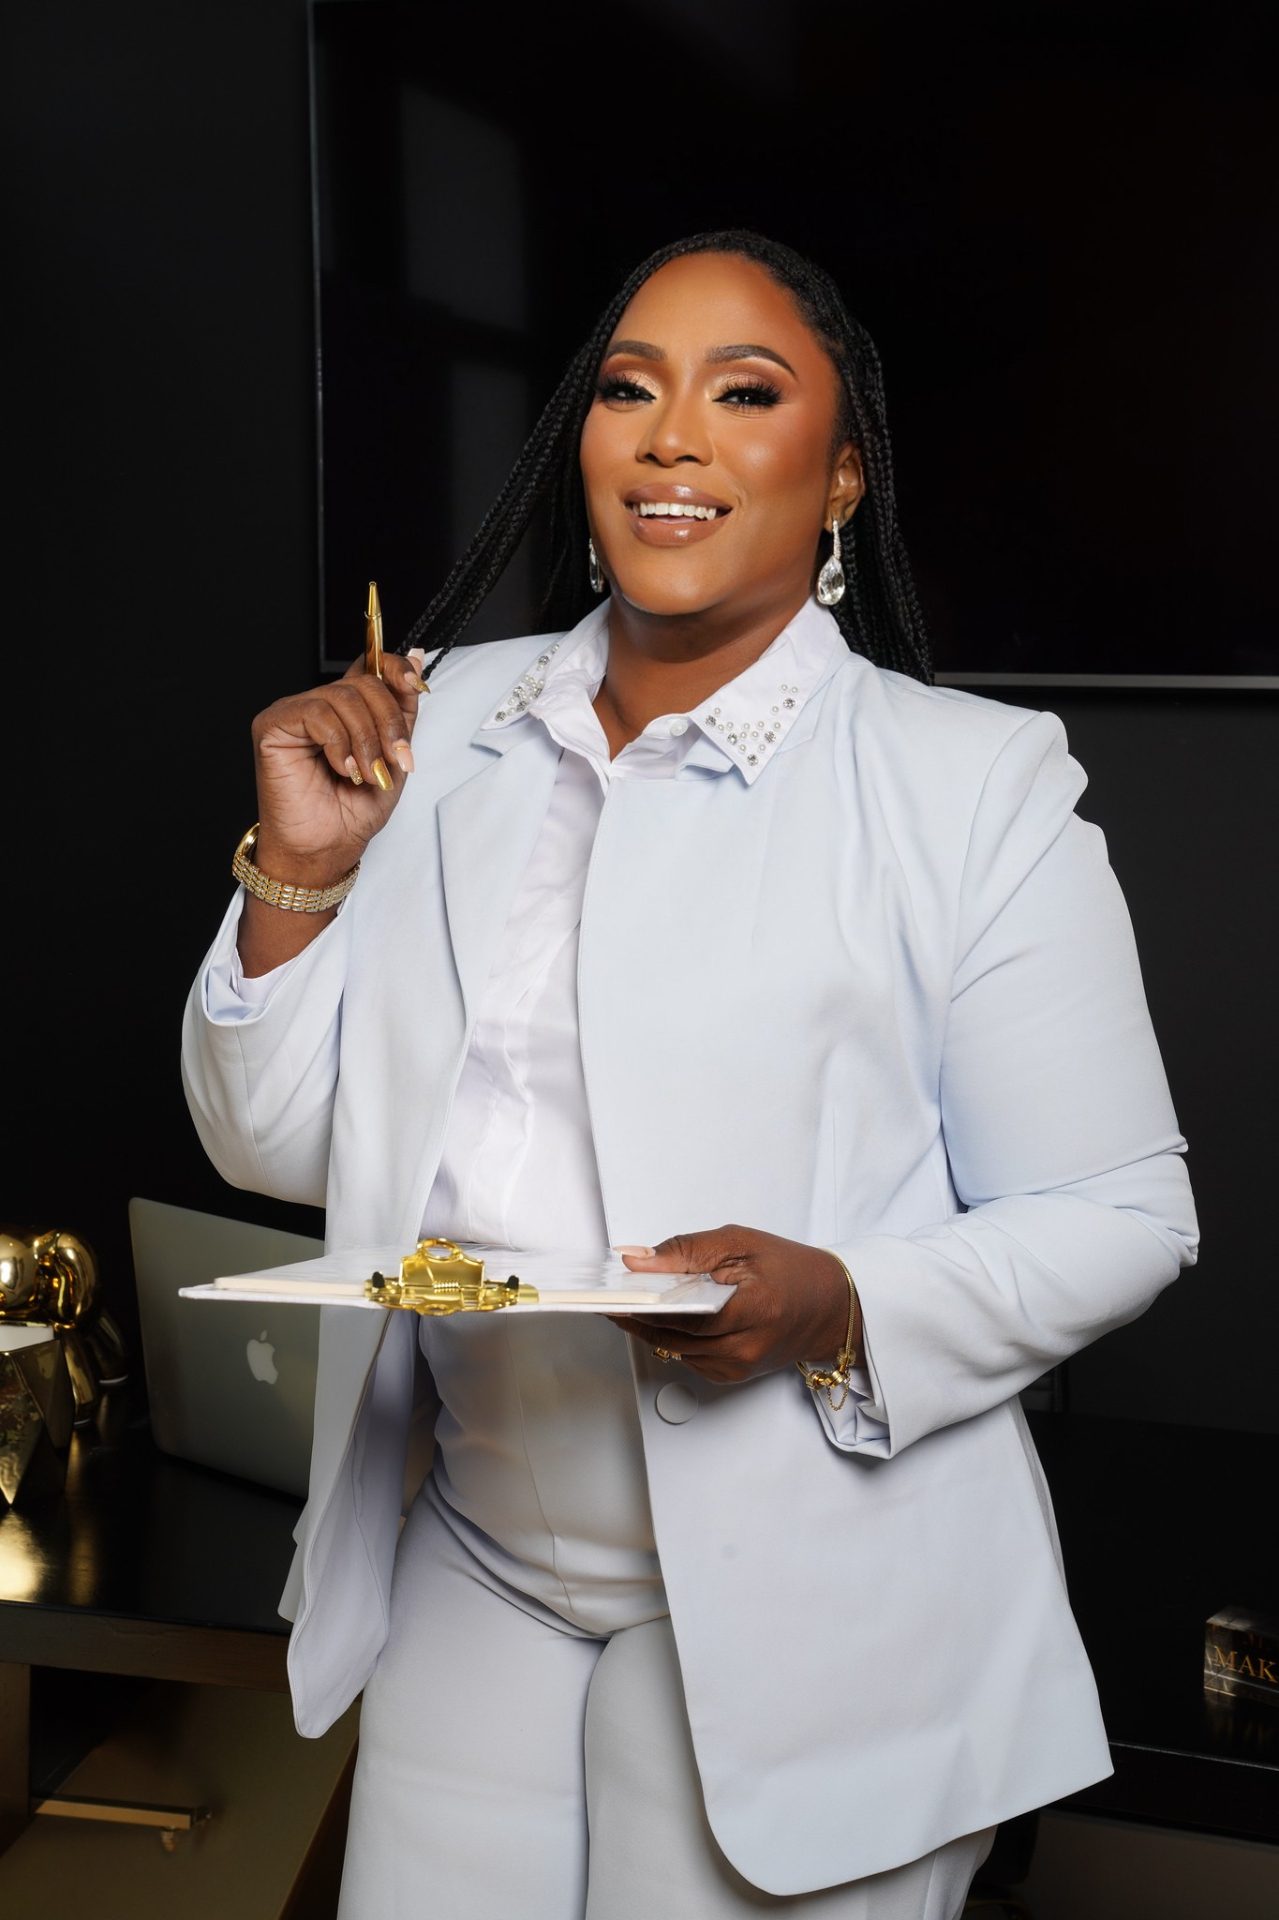
I created the Empire Roadmap for women business owners at $15K+ a month who are done with an LLC that stopped at the filing, and want business credit in their company's name. The average woman in your position has already paid an online filing service to form her LLC, sat through a "business credit in 30 days" webinar, bought a net-30 vendor list, and maybe put a deposit down with a funding company that only took her application. She came to me still guaranteeing everything personally, still guessing whether her business is fundable, and frustrated.
I created this to be the last stop on your journey.
You've probably lived at least one of these
The Guessing Problem
You don't know where your business actually stands. You think you're "probably fundable" because you're making money, but you've never seen your business through a lender's eyes, and every place a lender looks tells a slightly different story: one address on the state filing, another on the bank account, a third on the website.
The free advice you've found tells you to "build business credit" without ever checking whether your business is set up to have any. So you apply, get declined or get a tiny limit, and never learn why. The decline goes on the file, and you're worse off than before you asked.
The LLC That Stopped
You have an LLC. The state says so. But the filing named you as the owner, so the business is legally just you with a different name. Every contract, every lease, every card is still a personal guarantee. If the business owes it, you owe it.
The online filing service was happy to take your money and stop there. Nobody told you the LLC was the first step of a foundation, not the whole thing. So you've been "in business" for years with a company that can't own anything, can't protect anything, and can't borrow anything on its own.
The Personal Credit Reflex
When the business needs money, you reach for your own credit. Your personal cards carry the inventory. Your personal score takes the hits. You've built a real business on a credit file that was never meant to carry one.
The funding companies you've tried only took an application; they didn't build a file. The "business credit in 30 days" programs sold you net-30 vendor accounts that report to nobody who matters. Both skipped the part where the company itself becomes the borrower.
Why you are really stuck
Your inbox is full of funding advice. Your feed is full of business credit experts. You've paid for the filing, sat through the webinars, bought the vendor lists, and maybe put a deposit down with a funding company, each one promising a different path to money for your business. You came away with pieces: a tradeline here, a tip there. Never a clear, complete map showing exactly how to get from an LLC that stopped at the filing to business credit reporting in your company's name.
You've put in the effort. What you've never had is one complete map. Until now.
But there's a much simpler and better way...
Why I built this
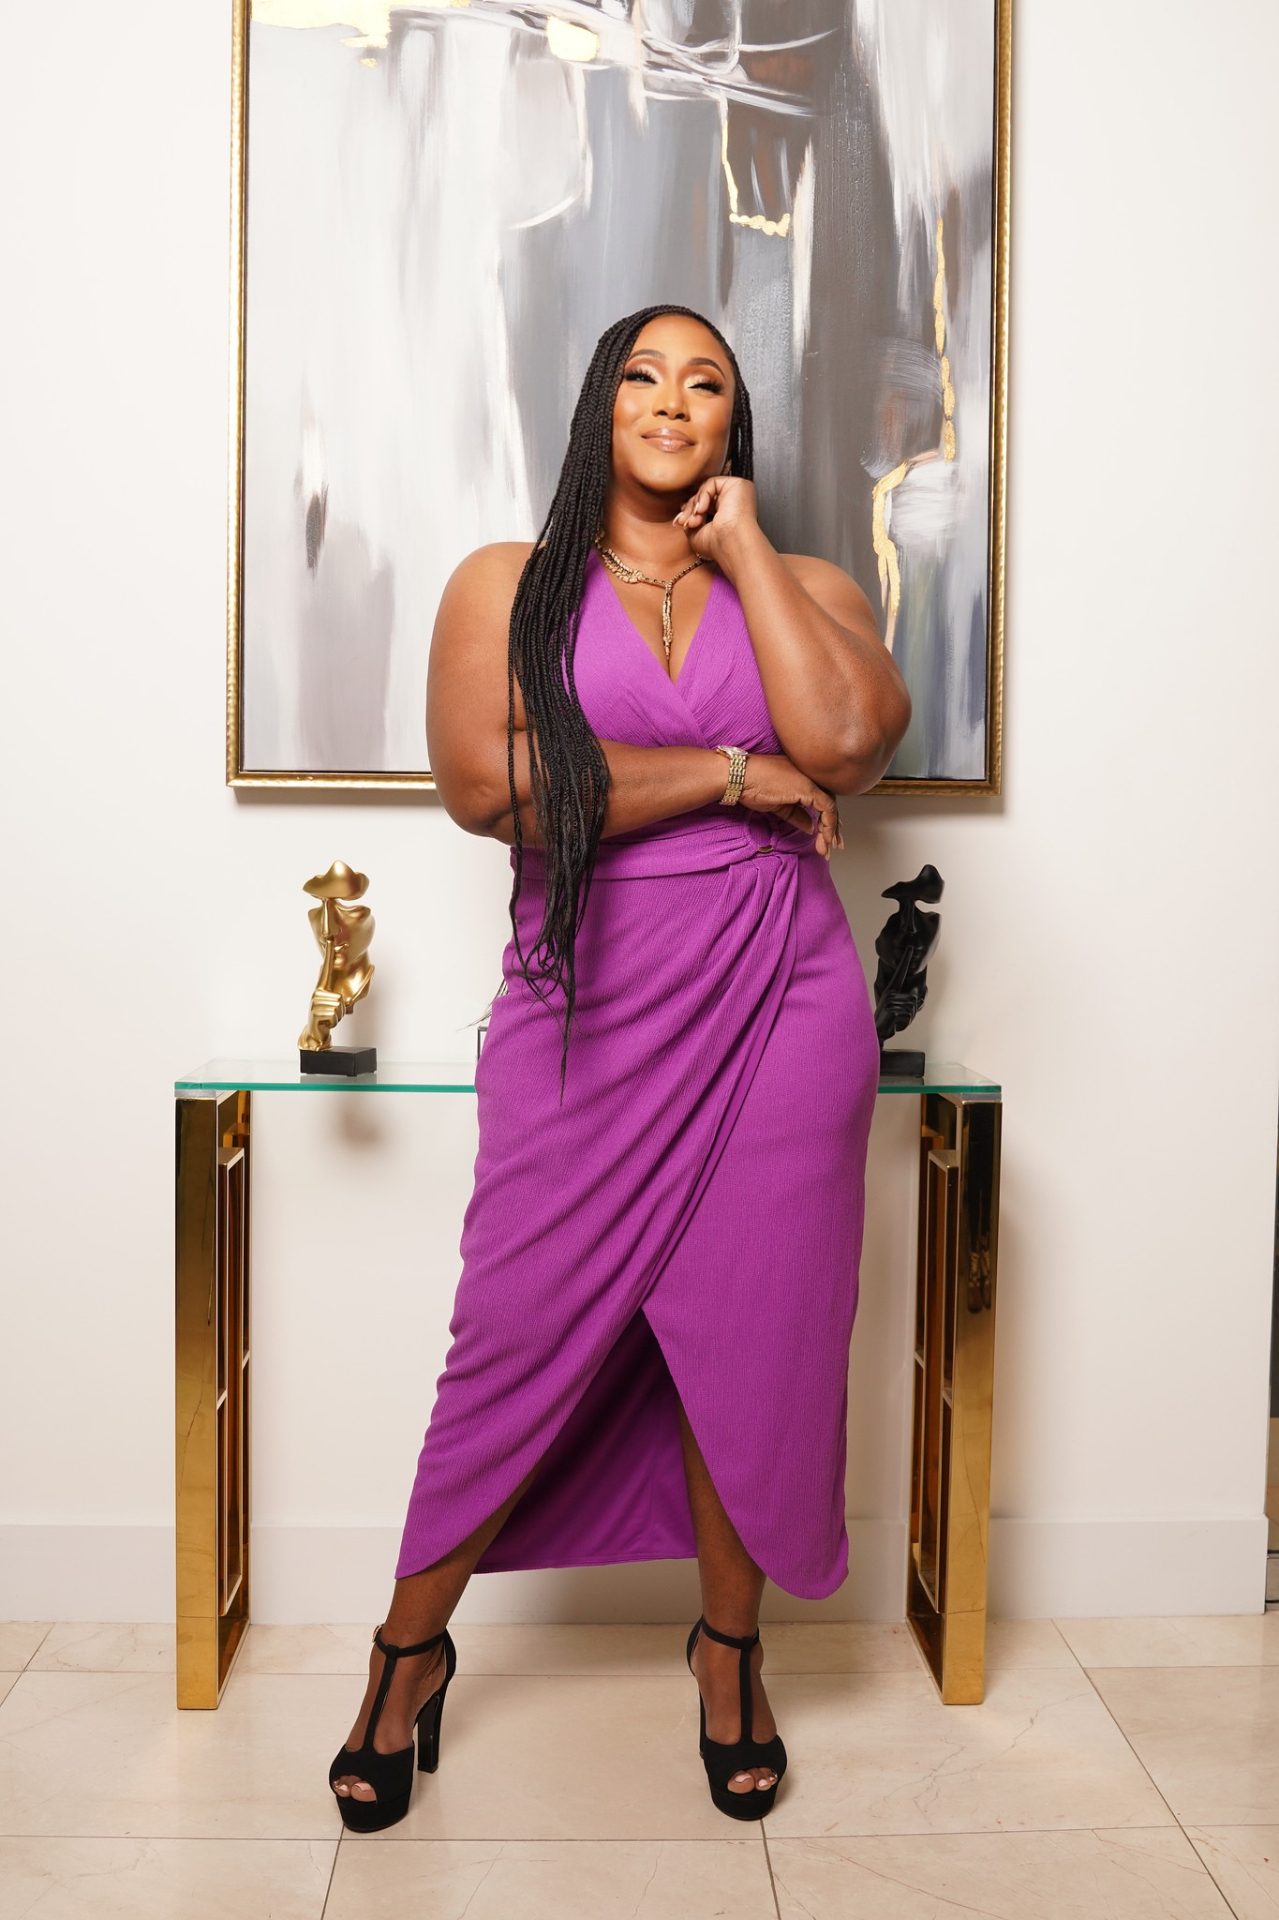
I'm a Business Developer, Funding Strategist, and Business Loan Broker with 500+ lender partners, and before that I was a compliance officer at the Florida Department of Business and Professional Regulation, working alongside the attorneys. I've placed $675,000 in funding for business owners. I built a case management agency from a single-member LLC into a group practice and then a full mental health hospital doing multiple seven figures.
And I lost it. Six years of building. Millions of dollars. My name in the community, my health, my family, and very nearly my marriage. The LLC was being converted to a corporation with a nonprofit added, but a problem with a contracted employee landed before the conversion processed, and the foundation couldn't hold the weight. My faith got low. It's also the only thing that kept me alive and brought me back.
The turn came years later, applying for funding for our construction company. It was doing over $200,000 and a big bank still turned us down; the only "yes" on the table was a merchant cash advance. So I sat with our business banker and asked her to walk me through how big banks actually decide. Six weeks of questions. By week two I saw it: it all starts with your foundation, and then with how you document the business, your income, your taxes, your profit and loss.
Funding was never my problem. Who owned the company was.
What my clients say
We filed her parent company and her nonprofit. Her 501(c)(3) letter came through, and she went on to receive grants, donations, and sponsorships for her after-school program.
Vernetta B., childcareComplete business foundation build, 2025. In her words: "She helps you, she pushes you, she tells you just like it is. I never would've made it this far with my business without her."
I created and launched my jewelry accessory line, adding additional cash flow to my salon.
Reva C., fashion accessory and healthcareCash flow is the first of the five funding lanes.
She has helped me create everything I needed to launch a movement with a marketing plan and strategies for my women's weekend conference.
Sandra W., nonprofit events
I have been working with her for over a year now. She gets and understands my vision and helped me to get on track to grow.
LaTasha T., mission-based coaching
My own results: a 20+ entity foundation across ministry, mission, and marketplace, built the way I teach it: a trust over a holding company over the operating companies, with the nonprofit beside them. $675,000 in funding placed for business owners as a Funding Strategist and Business Loan Broker with 500+ lender partners.
These women showed up, did the work, and followed the system. Your results will depend on your effort and how consistently you implement. Funding outcomes depend on qualifications, documentation, credit profile, lender criteria, and business structure.
The Trinity Structure
You've filed the LLC. Maybe you've sat through the "business credit in 30 days" webinar, opened a few net-30 vendor accounts, and handed a funding company your application. And here's why none of it stuck: every one of those started with the business as it is, a company that you own personally. Lenders see that. They see a business that is, on paper, just you.
Then I built the Trinity Structure. It's a foundation with three layers: a trust at the top, a parent company under it, and your operating company under that, with a nonprofit standing beside it if your work has a mission arm. The company that does the work is owned by a company, not by a person. That one change is what lets a business borrow, build credit, and hold assets in its own name.
Most women are still doing what the filing service told them: one LLC, their name on the ownership line, and then "build credit" on top of that. The Empire Roadmap works differently because we fix who owns the company first, and start the credit clock in month one, before we ever ask a lender for anything. Foundation, then documentation, then funding. In that order, because that is the order the banks use.
And once you understand how the Trinity Structure works, the entire system clicks into place. Here's the complete picture...
The company that does the work is owned by a company, not by a person.
Introducing the Empire Roadmap™
The complete 9-step system designed to take women business owners at $15K+/month from an LLC that stopped at the filing to business credit reporting in their company's name, in 90 days.
Align
The business tells one story before anyone checks it
The Fundability Score
Know exactly where your business stands on foundation, financials, credit, and capital readiness, with the three fixes that move it, in under 15 minutes.
The Trinity Funding Decision
Walk away with your ownership map drawn: which company owns what, where the trust sits, and whether a nonprofit arm belongs in your foundation.
The Credit Clock
Your D-U-N-S number is issued, your business name and address match everywhere a lender looks, and your first two reporting tradelines are open by day 30.
Structure
"I have an LLC" becomes "I have a company"
The Parent Company
Your parent corporation is filed and your operating LLC is owned by it, not by you. Your name comes off the ownership line.
The Empire Binder
Operating agreement, bylaws, first board minutes, and the written agreement between your company and your nonprofit, signed and in one binder.
The Clean Break
Business money only touches business accounts, your books are live in software, and every new contract is signed by the entity, not by you.
Fund
Foundation becomes fundable
The Lender-Ready File
One folder holds your use-of-funds statement, twelve months of bank statements, current tax filings, and a P&L. Every application from here pulls from it.
The Own-Name Proof
Your business credit report exists, tradelines are reporting in your company's name, and your personal credit cleanup is running alongside it.
The Five Lanes
Your five-lane map shows which of cash flow, grants, financing, government contracting, and sponsorships is open to you today, and your first applications are submitted.
Each step builds on the last. By the time you reach Step 9, you'll have business credit reporting in your company's name, a lender-ready file, and your first applications in, 90 days from the day you started.
Your 90-Day Business Credit Mapping Session
The next step is a 60-minute 90-Day Business Credit Mapping Session, and here is exactly what you walk away with:
Business consultants charge $200 to $400 an hour for generic advice. This is 60 minutes of personalized work on your company's foundation and fundability, with a written plan you leave with either way.
A nine-step fundability score of your business, from who owns your company to whether credit is reporting in its name, scored the way a lender reads it
$300Your one biggest gap, named, with a Funding Strategist's honest read on what it's costing you
$200Your custom 90-day map: the exact order of moves for your foundation, your documentation, and your funding, built for your business, not a template
$400A written before-and-after report you keep, to take to your attorney, your CPA, or your banker
$250Before you book, read this
I need to be upfront about something. The Empire Roadmap is work. It won't work if your business isn't producing real revenue yet; a foundation needs something to hold up. It won't work if you're looking for a loan by Friday. And it won't work if you aren't willing to put your business paperwork in front of someone, hear an honest read, and do the moves in order.
If you're still reading, here's who makes a great fit:
- You're a woman business owner doing $15,000 a month or more, and you have an LLC you formed and never touched again
- You're willing to open the filing, the bank statements, and the tax returns, because the score is only as honest as what you bring
- You can hear "your name is on the ownership line and that's the problem" without taking it personally
- You'll do the steps in the order the banks use: foundation, then documentation, then funding, even when the funding is the part you want first
If you can't see 60 minutes with me being worth ten times the $197, don't book. This is for women business owners who are serious about business credit in their company's name.
Where do you start? That's what we figure out together.
You've just seen the complete system. Three stages, nine steps, and the exact path from an LLC that stopped at the filing to business credit reporting in your company's name.
Now here's the question: where do you start?
A $197, 60-minute working session where I personally:
From who owns your company to whether credit is reporting in its name, the way a lender reads it
And give you my honest read on what it's costing you
The exact order of moves for your foundation, your documentation, and your funding
You keep, to take to your attorney, your CPA, or your banker
It's a working session, and I run it like one. You'll walk away with a clear, personalized plan whether we work together beyond this or not.
If we both agree there's a fit, I'll show you how Build Your Empire works, and your $197 is credited in full toward it if you enroll within 14 days. If not, you leave with a plan worth far more than $197.
Think about it. $197 for 60 minutes with someone who worked compliance at the Florida DBPR next to the attorneys, and who has lost a seven-figure business to the ownership line. This is customized work on your company.
You've probably already spent more than $197 on the filing service that stopped at the filing, or the "business credit in 30 days" webinar, or the net-30 vendor list. None of them looked at your foundation. This does.
The session pays for itself in clarity alone.
I open five builds a month, first come, first served. When the five are taken, the next Mapping Session I run is for the month after. And the $197 credit toward Build Your Empire holds for 14 days after your session, not longer, because the plan we build is dated, and business credit files start reporting on a clock that starts the day you do.
The choice is yours.
You can keep guessing whether your business is fundable, keep signing everything personally because your name is still on the ownership line, and keep reaching for your own credit every time the business needs money. Or you can fix who owns the company first, the way the Trinity Structure does, and get business credit reporting in your company's name. Start building something that stands on its own foundation while you run your business.
Book your Mapping Session, $197
P.S. Vernetta came in with an LLC and her name on the ownership line. We filed her parent company and her nonprofit, and she went on to receive grants, donations, and sponsorships for her after-school program. Sixty minutes, $197, and you leave with the map. → calendly.com/drlyndabarnes/empire-mapping-session
P.P.S. Still not sure? Email me at [email protected] with the subject line "Empire Roadmap Question." I read every one.